





The Month in Review - October 2025
Monthly Review
Farrow Hughes Mulcahy Investment Research 07 November 2025

International shares continued their upward trend, while Australian shares posted modest gains.
Performance Summary:
MSCI World Index: +3.3%
Australian Shares: +0.4%
US Market and Federal Reserve Update
The meeting between Trump and Xi was positive, though markets expected more. US earnings were strong overall, despite some tech sector weakness. The Federal Reserve cut interest rates by 25 basis points for the second consecutive month, bringing the Fed Funds rate to 3.75 - 4%. This marks a total reduction of 150 basis points since September 2024. While some members advocated for a larger cut, others preferred no change. The Fed noted slowing labor markets, rising inflation, and moderate economic growth, signaling a cautious approach to future cuts.
Japan and Europe
The Bank of Japan kept rates unchanged, with Governor Ueda indicating more data is needed before any hike, though a December increase remains possible. The Yen faced downward pressure following the decision.
The European Central Bank held rates steady at 2% for the third consecutive meeting. Eurozone GDP grew 0.2% in Q3 and 1.3% year-on-year, with strength in Sweden, Portugal, and France offset by weakness in Germany, Ireland, and Finland.
Australia
High September quarter inflation data signaled no chance of a rate cut at the recent RBA meeting and raised doubts about future cuts. Governor Bullock emphasized a high hurdle for further easing, suggesting another cut may not occur until well into next year. Current low rates should help dampen home price growth.
US Earnings
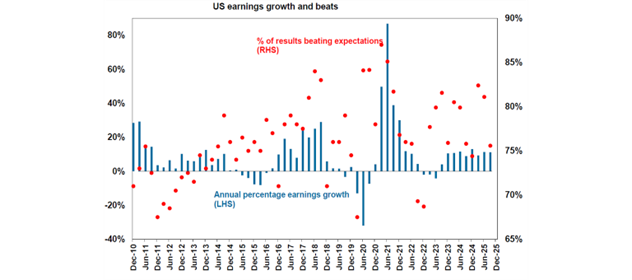
US tech earnings were mixed this quarter. Of the 61% of companies that reported, earnings growth averaged 11%, with 76% beating expectations. Alphabet outperformed on strong cloud results, while Meta faced pressure from rising expenses tied to AI and data centers. Apple and Amazon posted positive results. Despite robust profit growth, high valuations suggest potential short-term pullbacks.
Outlook for Investment Markets
- Share markets remain vulnerable to corrections due to stretched valuations and trade risks, but supportive policies and potential rate cuts should drive moderate gains over 6–12 months.
- Bonds likely to deliver returns near running yield as central banks ease further.
- Unlisted commercial property expected to recover as office prices stabilize.
- Australian home prices rising, though constrained by affordability and gradual rate cuts.
- Cash and deposits projected to return around 3.5%, with a slowing trend.
- AUD may face near-term volatility from US tariffs but could strengthen medium-term, supported by undervaluation (fair value around US$0.73).
Important Note: While every care has been taken in preparing this document, Farrow Hughes Mulcahy makes no representations or warranties as to its accuracy or completeness, including forecasts. Past performance is not a reliable indicator of future performance. This document provides general information only and does not consider individual objectives or financial situations. Professional advice should be sought before making investment decisions.
Source: AMP Capital, Zenith.
